
THE BANK ACCOUNT MADE NO SENSE.
A $2.3M fiber splicing subcontractor had skilled crews, major telecom carrier clients, and a bank account nobody could explain. Some months looked strong and some looked like a disaster, and nobody could predict which. Project costs were posting to the wrong places, so nobody could see the real numbers. One winter month had $141,000 of project cost against $144,000 of revenue. That leaves almost nothing before overhead. The owner now reads his own numbers every month and knows what his T&M rate has to be.
Time and material fiber work comes in bursts. A carrier releases a batch of splicing and the crews work hard. Then the schedule thins out, and overhead stays where it was during the busy stretch. The rates were built on busy month numbers, with no honest look at utilization across a full year. So the price was right for the best month and wrong for the year. His wife kept the books after hours, and nobody was careless. Subcontractor accounting is complex, and nobody can see a cost coded to the wrong place. This study has no dollar recovery figure. The outcome is that the owner can see the business. Every dollar figure on the other studies started there.
- Revenue
- $2.3M
- Before
- Project costs posting to the wrong places. One winter month had $141,000 of project cost against $144,000 of revenue.
- After
- The owner reads his own financials every month and knows what his T&M rate has to be.
- Time
- The standard 60 day onboarding.
- Result
- No dollar recovery figure. The outcome is visibility and a corrected pricing basis.
A $2.3M FIBER SUB. AND A BANK ACCOUNT NOBODY COULD EXPLAIN.
A fiber splicing subcontractor doing $2.3M a year, working time and material for major telecom carriers. The crews were skilled and the client list was one most subs would want. Some months the bank account looked great and some months it was a disaster. Nobody could say ahead of time which one was coming.
THE BANK ACCOUNT MADE NO SENSE.
The revenue was there. The work was there. The owner couldn't explain how the account balance related to either one. A good month and a bad month looked about the same going in, and very different coming out.
His wife kept the books after hours, and she was careful. Subcontractor accounting is complex: job cost coding, work in progress, and material against labor on time and material tickets. Project costs were posting to the wrong places. A cost in the wrong place doesn't tell anybody it's there.
So nobody could see the real numbers. Pricing came from memory of how the busy months felt. Nobody could say which months made money and which ones used up what the good months earned.
PRICED FOR THE BUSY MONTH, PAID FOR THE WHOLE YEAR.
Time and material fiber work comes in bursts, and overhead doesn't stop between jobs. A month with a full schedule covers overhead easily. A month with a thin schedule covers none of it. The year is the average of the two.
The rates were built on busy month numbers, with no honest look at utilization across a full year. So they covered overhead only in the months that were already working. One winter month shows it best: $141,000 of project costs against $144,000 of revenue. That leaves almost nothing before overhead is paid.
The Job Profitability System wasn't in place. Project costs were posting where they didn't belong. So no job and no month could be compared to its price. You can't correct a billing rate from a total that mixes everything together.
WHAT CHANGED, WEEK BY WEEK.
THE NUMBERS, NOT THE FEELING.
This study has no dollar recovery figure, and we won't invent one. What changed is what the owner can see. He reads his numbers every month. He knows which months make money and which ones use up margin. He knows what his T&M rate has to be. He's building out structured cabling work, which is contracted and bills predictably, to even out revenue next to the time and material. His decisions now come from what the business is doing.
Total time from first call to a monthly close the owner reads himself: the standard 60 day onboarding. There's no debt payoff date to report here. The outcome is that the owner can see the business, and his pricing basis is corrected.
TEN MONTHS IN, NET PROFIT IS UP 7X.
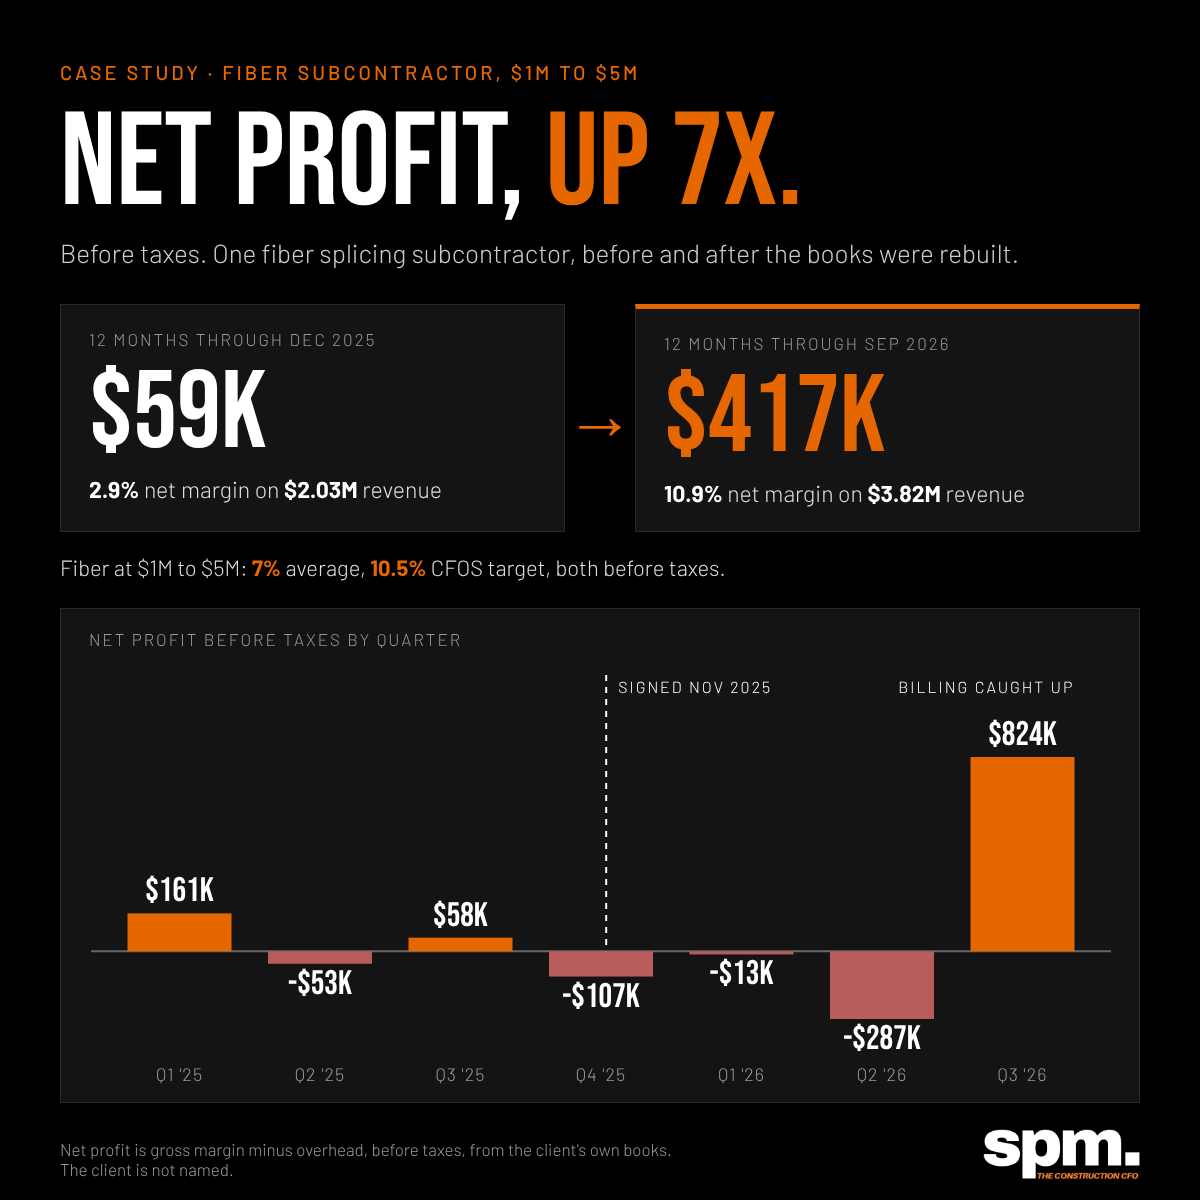
We signed this contractor in November 2025. The CEO Report for the twelve months through December 2025 showed $2.3M of revenue and $59K of net profit before taxes, a 2.6 percent net margin. The report for the twelve months through September 2026 shows $3.82M of revenue and $417K of net profit before taxes, a 10.9 percent net margin. The fiber average at $1M to $5M is 7 percent and the CFOS target is 10.5 percent, both before taxes.
The 2025 books showed a gross margin of about 73 percent and overhead of about 70 percent of revenue. That was never a great margin. Project cost was posting to overhead. That made the jobs look better than they were and the office look heavier than it was. With project cost on the jobs, the last twelve months show a 44 percent gross margin and 33 percent overhead. Both numbers now mean something.
It wasn't a straight line, and the chart shows that. The first half of 2026 lost $300K before taxes, most of it in March, April and June. Part of that was billing. They were behind on sending invoices, so the cost of the work was on the books before the revenue was. The owner saw it in his monthly report, by job, and didn't have to wait for tax time. They caught up on billing in July, and July revenue alone came to $1.06M. The third quarter of 2026 brought in $2.25M of revenue and $824K of net profit before taxes. Some of that quarter is work done earlier in the year. That's why the twelve month figures are the fair comparison: $59K before, $417K after, both before taxes.
The balance sheet followed. From December 2025 to September 2026, equity went from $103K to $627K, working capital from $35K to $821K, and the current ratio from 1.68 to 3.61.
DOES THIS SOUND FAMILIAR?
This applies to any contractor whose work comes in bursts. Time and material splicing, service calls, storm response, and on call maintenance are all like this. Somebody else's release schedule sets your month. Overhead stays the same whether the crews are out or not. And the rate on the ticket was set during a stretch that felt busy.
The first sign is a bank account that doesn't match how the work felt. If a strong month and a weak month end with the same balance, or the opposite of what you expected, the costs aren't posting where the work happened. Every price built on that is a guess. The second sign is a spouse keeping the books at night. Subcontractor accounting needs somebody whose whole job it is.
The figures on this page came from this client's own books. No client is identified anywhere on this site. The carriers, the markets, and the projects stay out too, because any two of those would identify a company in a regional trade.
See how CFOS applies to fiber subcontractors specifically on theCFO for Fiber Contractors page, or book a 20 minute call. Josh won't pitch you or send a proposal.
FREQUENTLY ASKED.
